


The market’s AI question has been about capital spending: how much, how fast and when it slows. A bigger number sits in the footnotes. It records what the companies have already agreed to pay, whatever happens to demand.
The other backlog
Besides the capital spending in their cash flow statements, the five biggest AI builders disclose two kinds of signed obligations that do not appear on their balance sheets. The first is purchase commitments, mostly for servers, chips, cloud capacity and power. The second is leases that are signed but have not yet started, mostly for data centers. We added them up from each company’s latest quarterly filing.
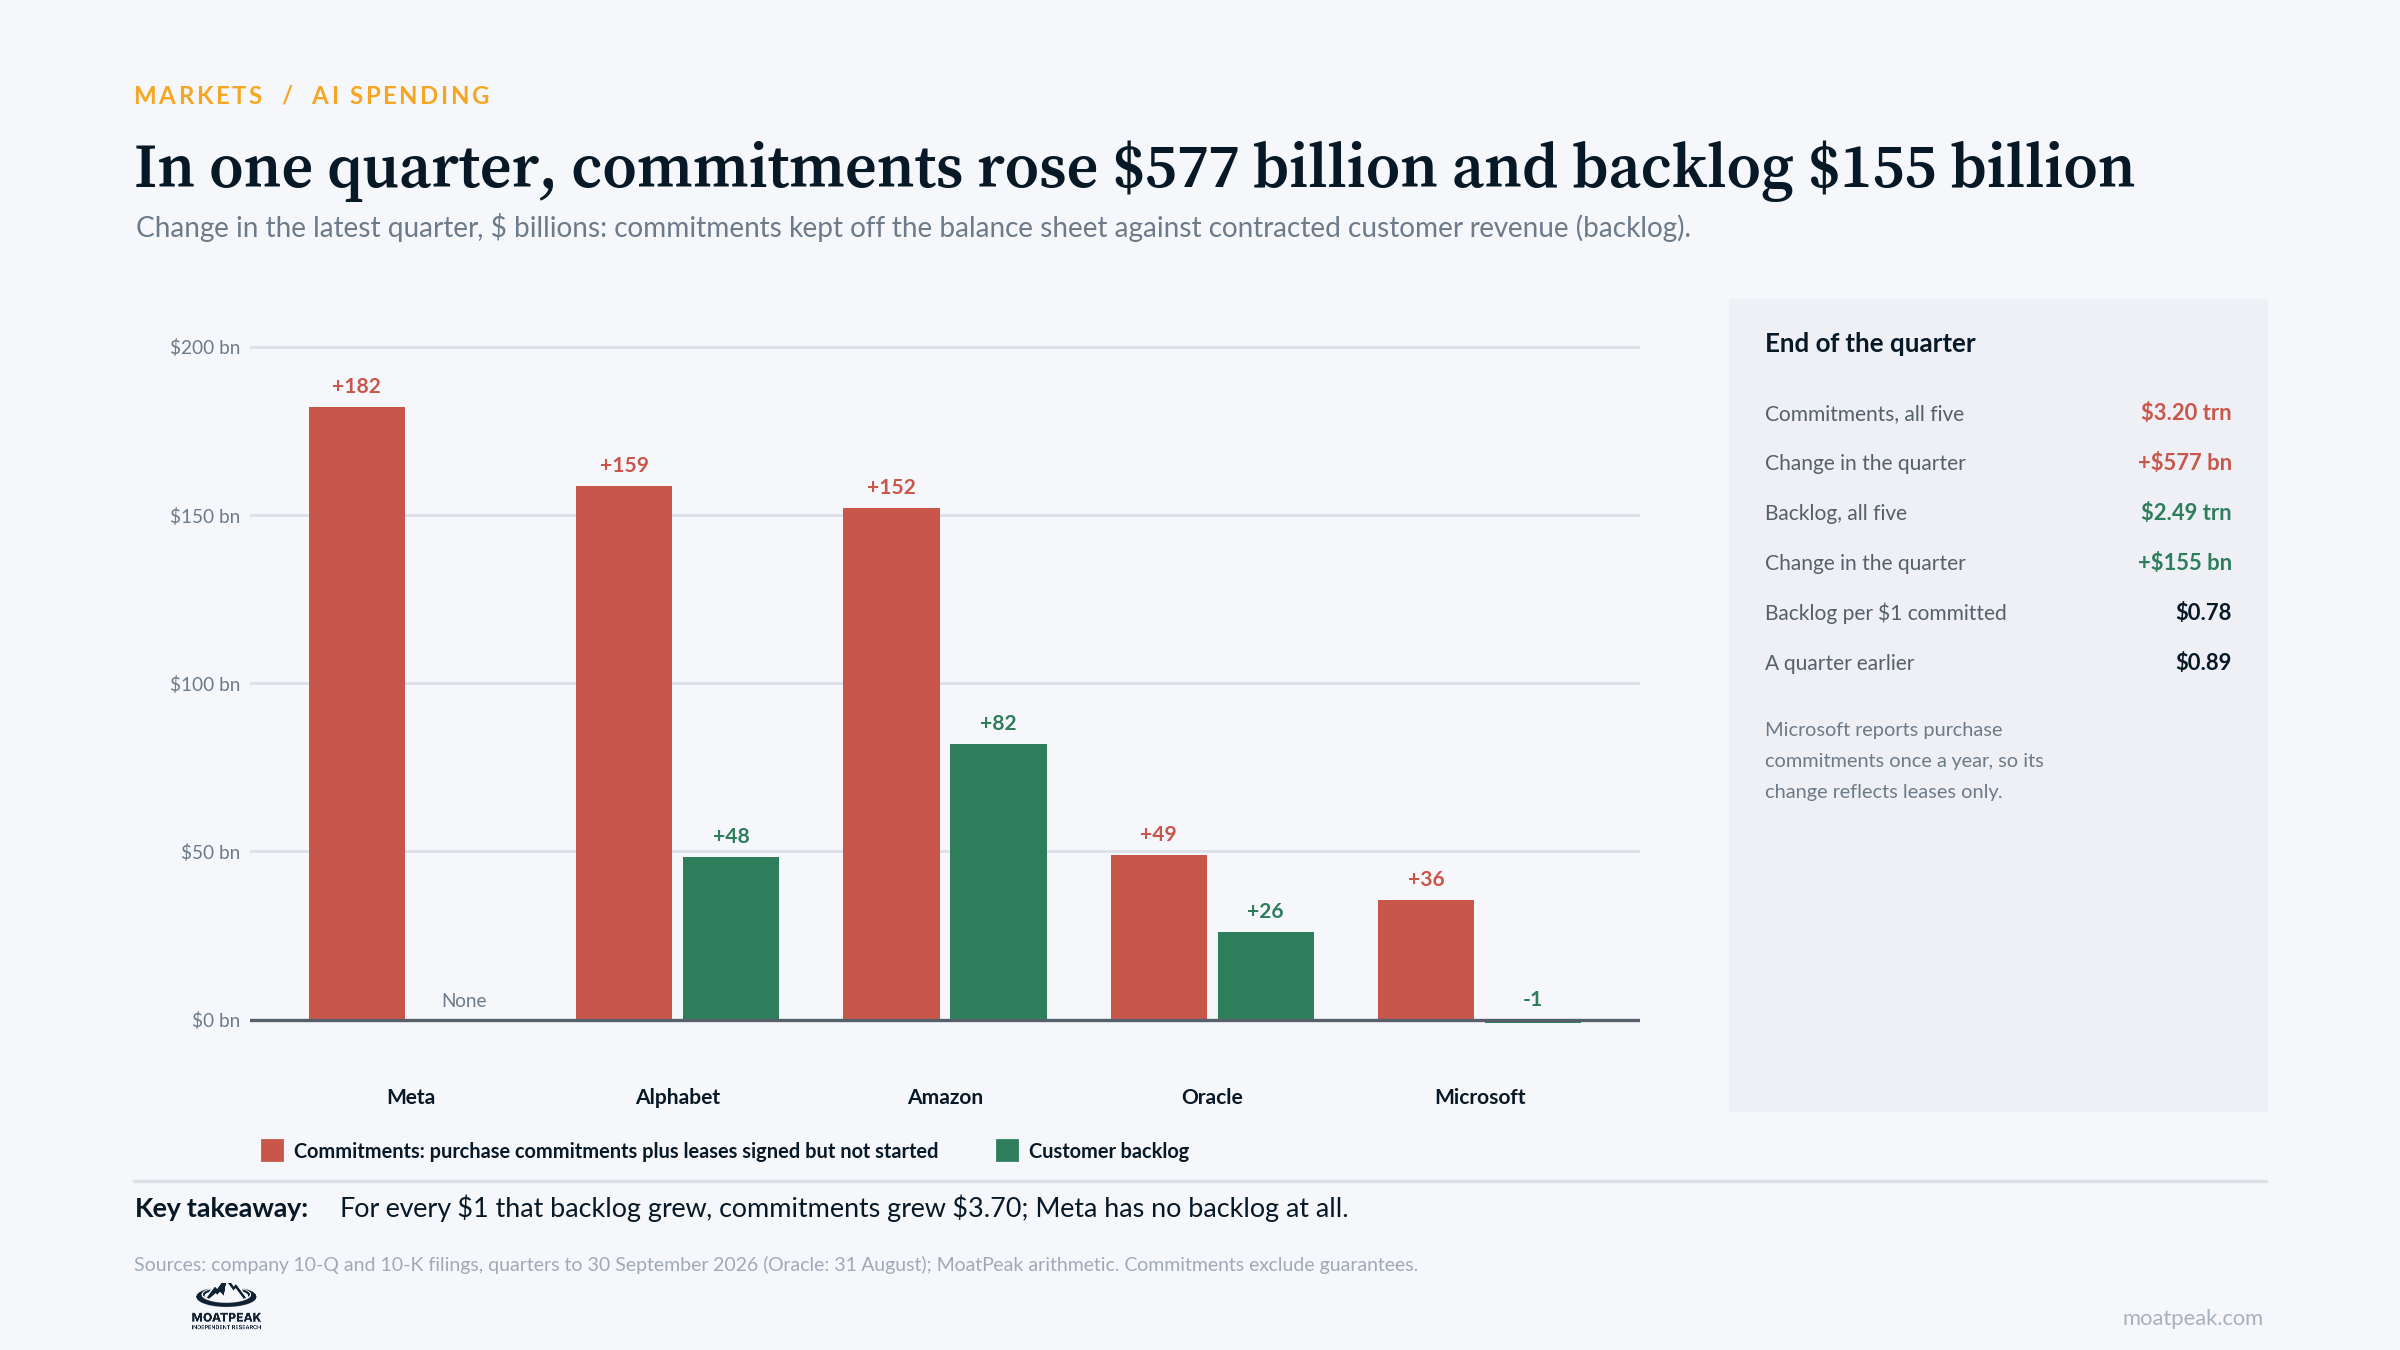
At the end of the September quarter (August for Oracle), the total was $3.20 trillion. Three months earlier, it was $2.62 trillion. That is a net increase of $577 billion, or 22 percent, in one quarter.
Meta added $182 billion, taking its total to $810 billion: $455 billion of non-cancelable purchase commitments, mostly for third-party cloud capacity and servers, and $356 billion of leases that have not yet started. Alphabet added $159 billion, to $1.05 trillion, of which $924 billion is purchase commitments, with $213 billion of those due within 12 months. Amazon’s total jumped 57 percent, to $419 billion, as its obligations to buy property and equipment and its other unconditional purchases nearly doubled to $254 billion. Oracle added $49 billion, to $322 billion, mostly in data center leases. Microsoft added $36 billion of leases, to $365 billion. It updates its $229 billion of purchase and construction commitments only once a year, in June.
What customers have signed
The cloud sellers also report the other side of the ledger: backlog, the revenue customers have contracted for but not yet been billed. Over the same quarter, backlog across the five rose $155 billion, to $2.49 trillion. Amazon’s grew $82 billion, Alphabet’s $48 billion and Oracle’s $26 billion. Microsoft’s slipped by $1 billion. Meta sells no cloud capacity, so it has no backlog to report.
For every $1 that backlog grew, commitments grew about $3.70. A quarter earlier, they held 89 cents of backlog for each dollar committed. Now they hold 78 cents.
Five different bets
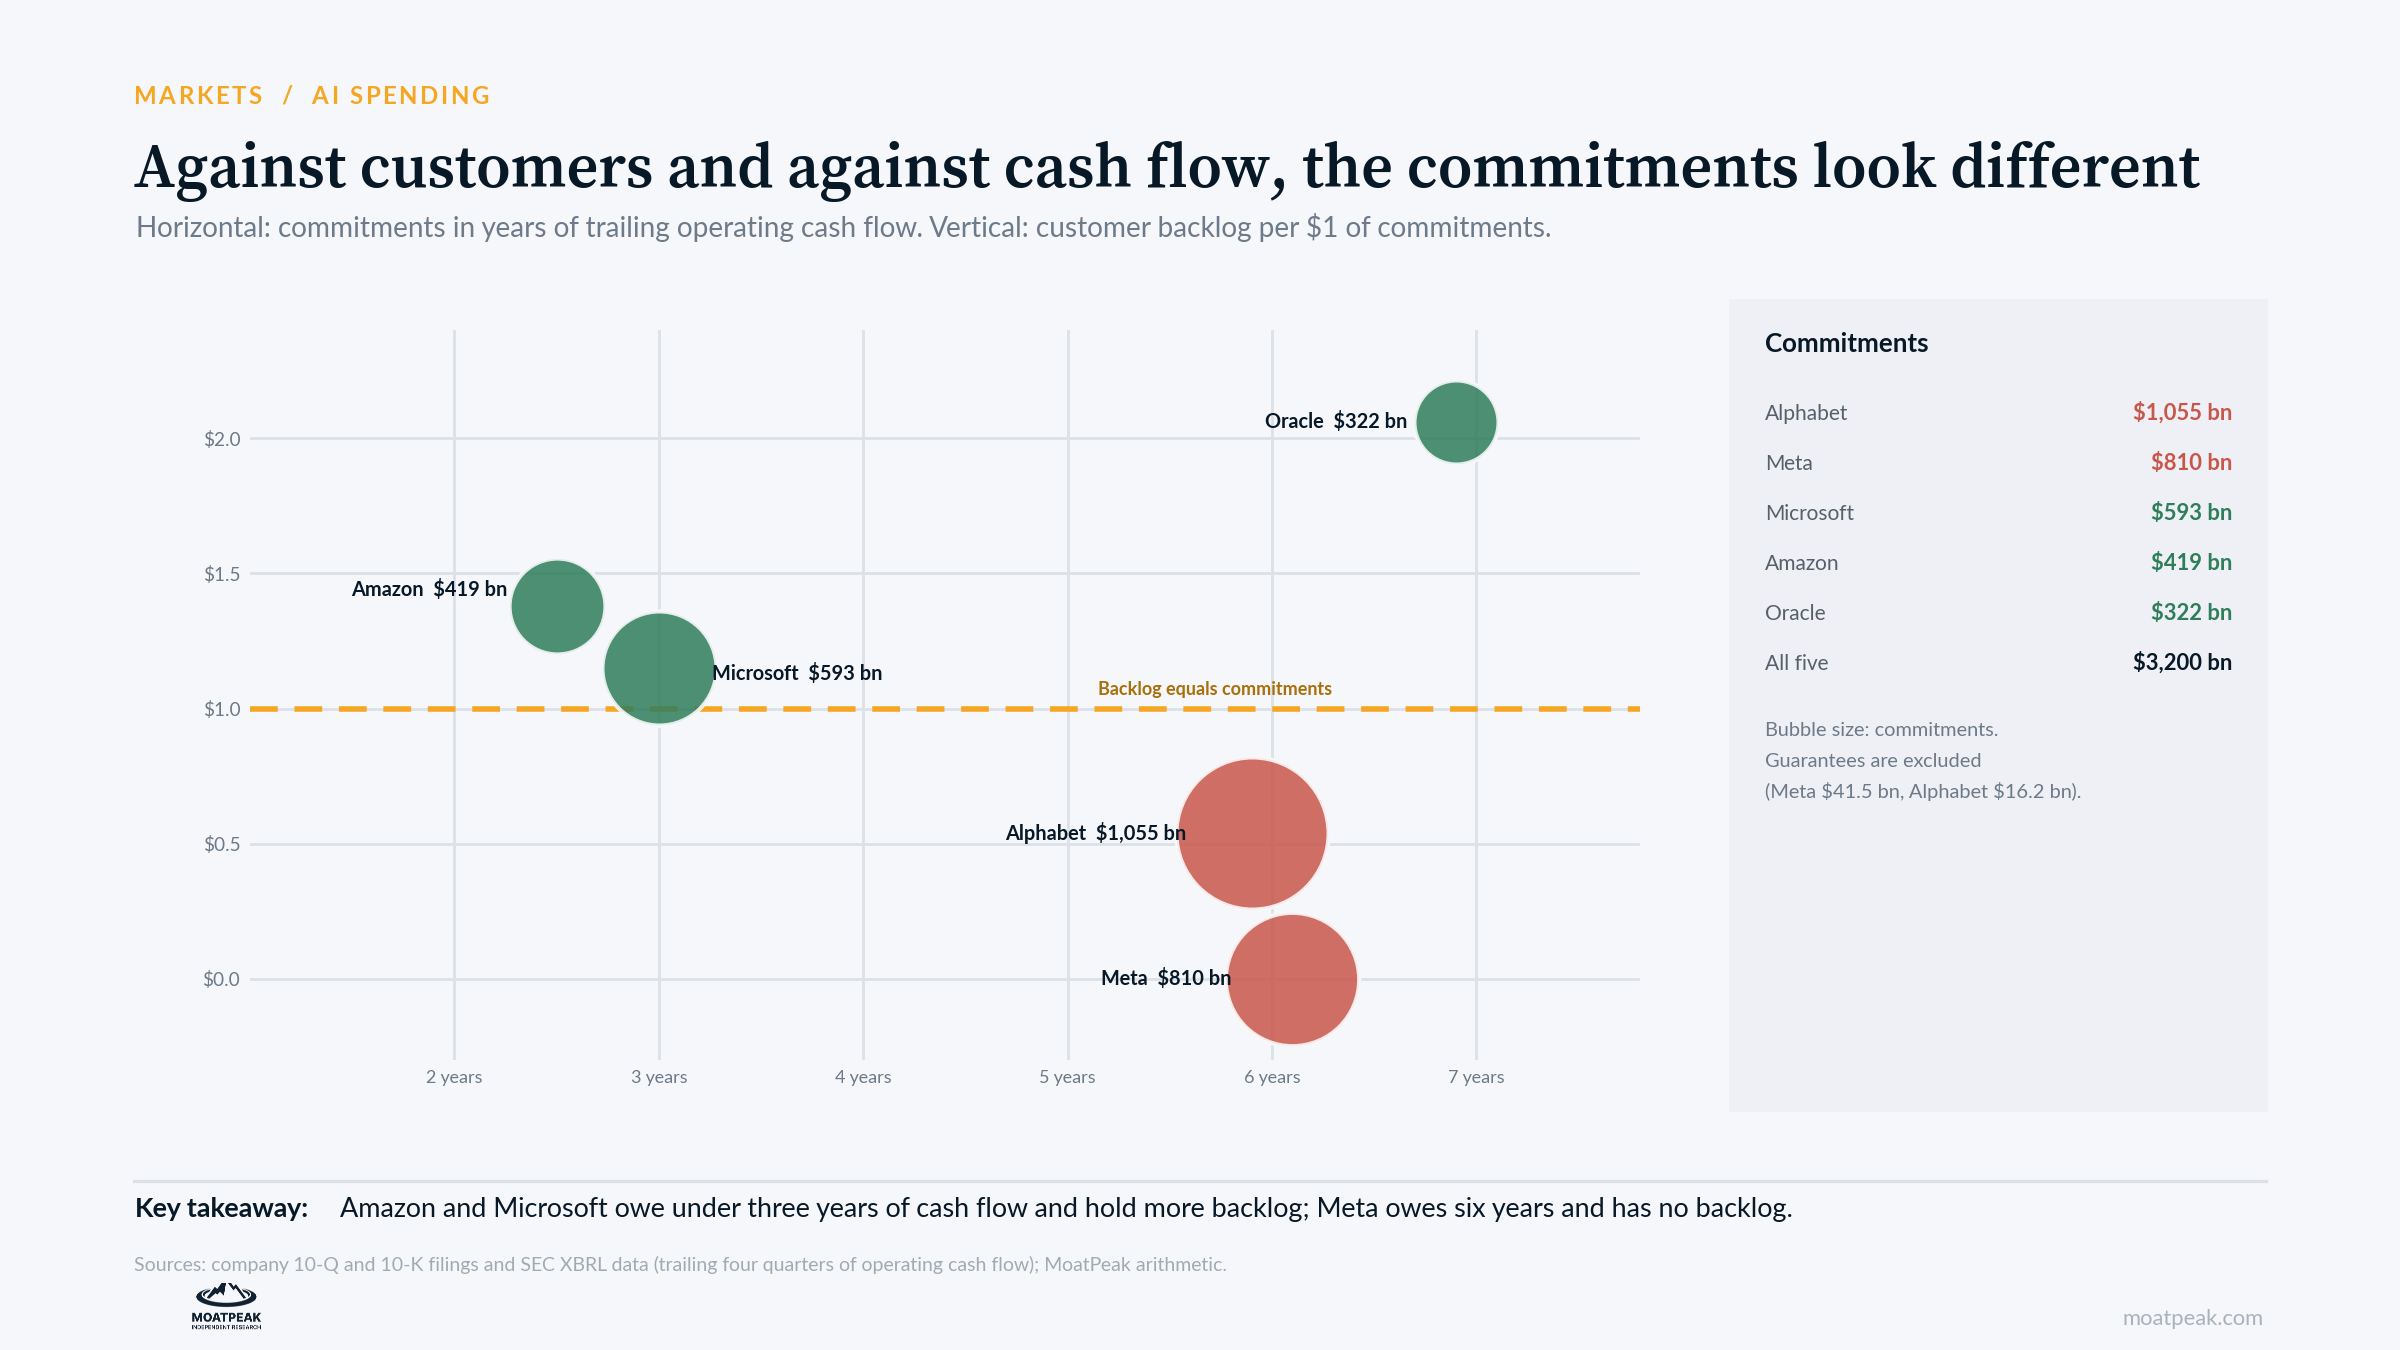
The total hides how differently the companies are placed. Two measures help. Backlog per dollar of commitments shows how much of the bill outside customers have agreed to cover. Commitments in years of operating cash flow show the size of the bill against the money each company generates.
Amazon and Microsoft sit in the safest corner. Their commitments equal 2.5 and 3.0 years of operating cash flow, and their backlogs exceed their commitments by 38 percent and 15 percent.
Oracle has the most customer cover, $2.06 of backlog for each dollar committed, but the heaviest load against its own cash: 6.9 years of operating cash flow. It is betting that a few large customers pay as contracted.
Alphabet and Meta are building mainly for themselves. Alphabet’s commitments equal 5.9 years of operating cash flow, with 54 cents of cloud backlog per dollar. Meta’s equal 6.1 years, with no backlog at all. Their main customer is their own advertising business.
Our read
The market treats capital spending as a dial that will turn down if AI demand disappoints. The filings show how much of that dial is already locked. Most of these commitments run for years. Meta’s leases start as late as 2036, and Microsoft’s as late as its 2034 fiscal year. Alphabet will fulfill most of its purchase commitments by 2031. If demand cooled tomorrow, the payments would continue.
That has two consequences. First, suppliers’ revenue is better protected than October’s selloff implied, because much of it is already contracted. Second, the risk falls on companies with no outside customers lined up. For Meta, and to a lesser degree Alphabet, the commitments are a bet that their own businesses will grow into the capacity.
Commitments are not debt. Most will be paid from operating cash flow as the capacity comes online, and much of the money buys assets that will earn revenue. They behave like debt in one respect, though: they are owed whatever the share price does.
The case against us
Building for internal use is not wasted effort. Meta and Alphabet run the world’s two largest advertising businesses, with operating cash flow of $133 billion and $180 billion over the past year.
Backlog is not cash either. Much of the cloud backlog comes from a handful of AI developers that must keep raising money to pay their bills. A contract with a customer that cannot pay covers nothing.
Timing differs. Commitments are paid over as long as 30 years, while our cash flow measure uses the past four quarters. It shows scale, and it is no test of solvency. Some leases also depend on conditions being met: Microsoft says some of its arrangements are subject to them.
What it means for your money
Track the coverage each quarter. Compare the change in commitments with the change in backlog. When commitments grow faster, the company is building ahead of signed demand.
Separate landlords from owner-users. Cloud sellers with backlog can pass costs on to customers. Companies building for their own products need their own revenue to grow into the capacity.
Read commitments as supplier revenue. Alphabet alone has $213 billion of purchase commitments due within 12 months, and Meta has $121 billion due in 2027. That supports chip, memory and power suppliers into 2027 even if new orders slow.
What we are watching
17 November: Nvidia’s results, the supplier side of these commitments.
Mid-December: Oracle’s next quarter, and whether its backlog keeps pace with its leases.
February: annual reports from Alphabet, Amazon and Meta, with full tables of obligations by year.
Educational research only. Not personalized investment advice. MB “MoatPeak Group”.
For Meta and Alphabet the real risk isn't solvency, it's the business model quietly changing. Both were valued as capital-light compounders, and $810 billion and $1.05 trillion of locked commitments turn them into something closer to utilities, where returns depend on filling the capacity.
The coverage ratio catches part of it. I'd put return on invested capital next to it, quarter by quarter, to see whether the ad business is actually growing into the build.