


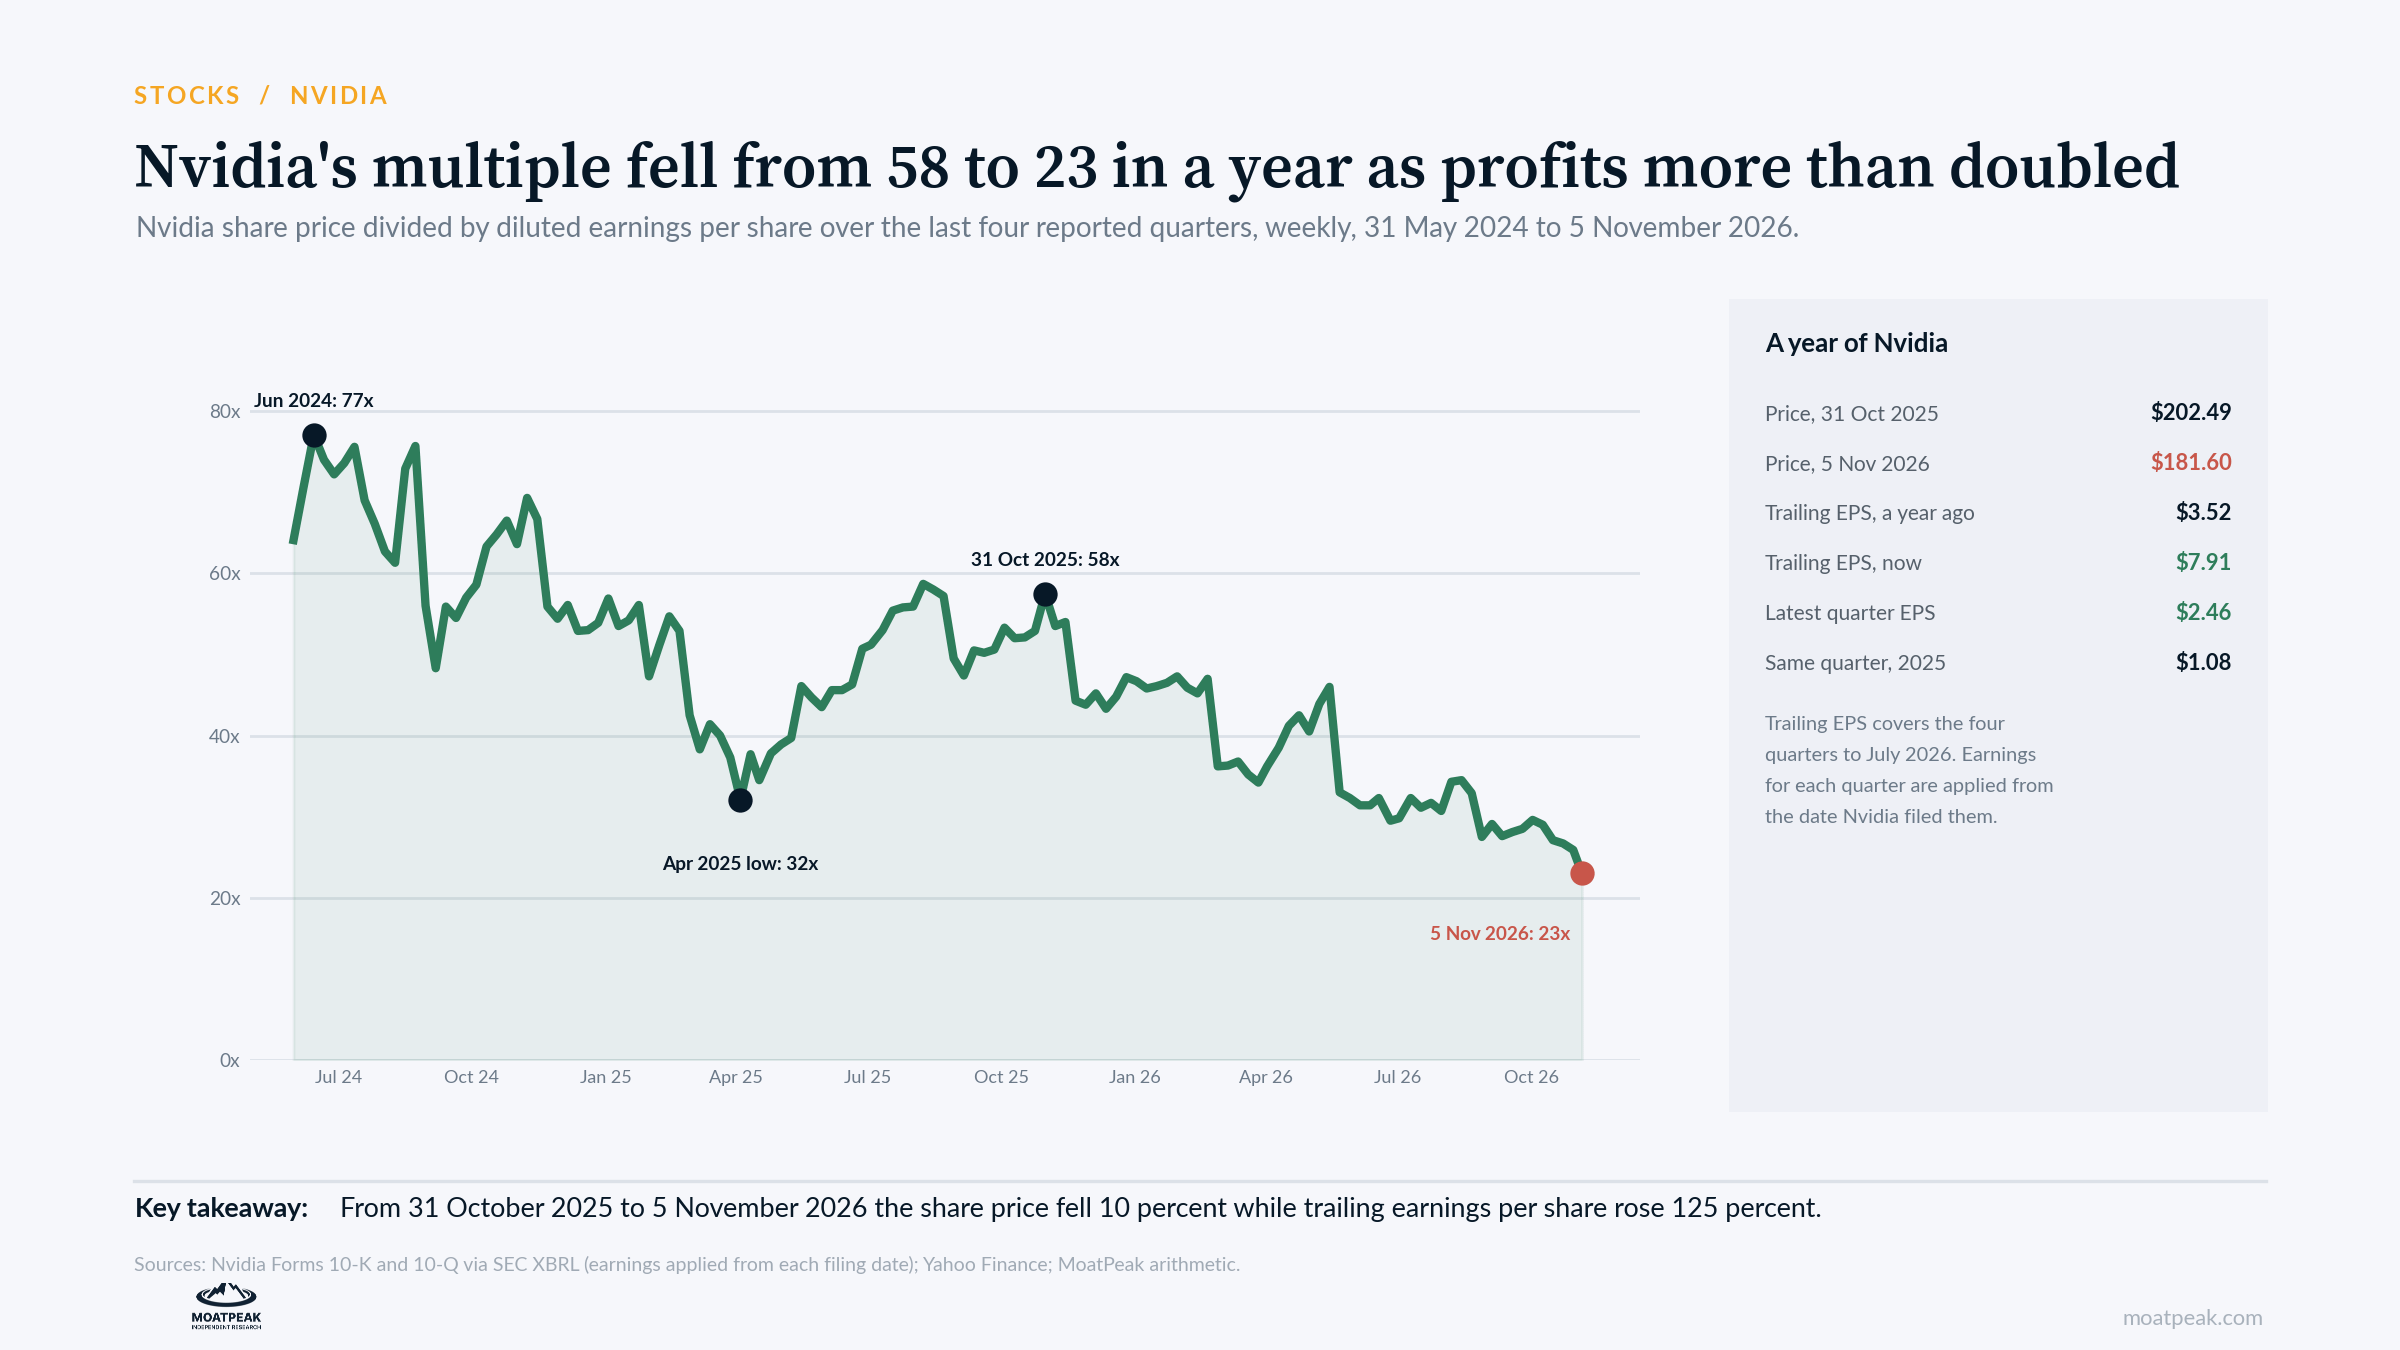
At the 5 November close, Nvidia’s shares stood 10 percent below their level at the end of October 2025. Over the same stretch, its trailing earnings per share, the total for the last four reported quarters, rose from $3.52 to $7.91, an increase of 125 percent.
When a stock falls while its profits more than double, its price-to-earnings ratio collapses. Nvidia’s fell from 58 to 23. On that measure, the company at the center of AI spending is now cheaper than Procter & Gamble, at 25, and Microsoft, at 28. Costco, at 51, costs more than twice as much per dollar of earnings.
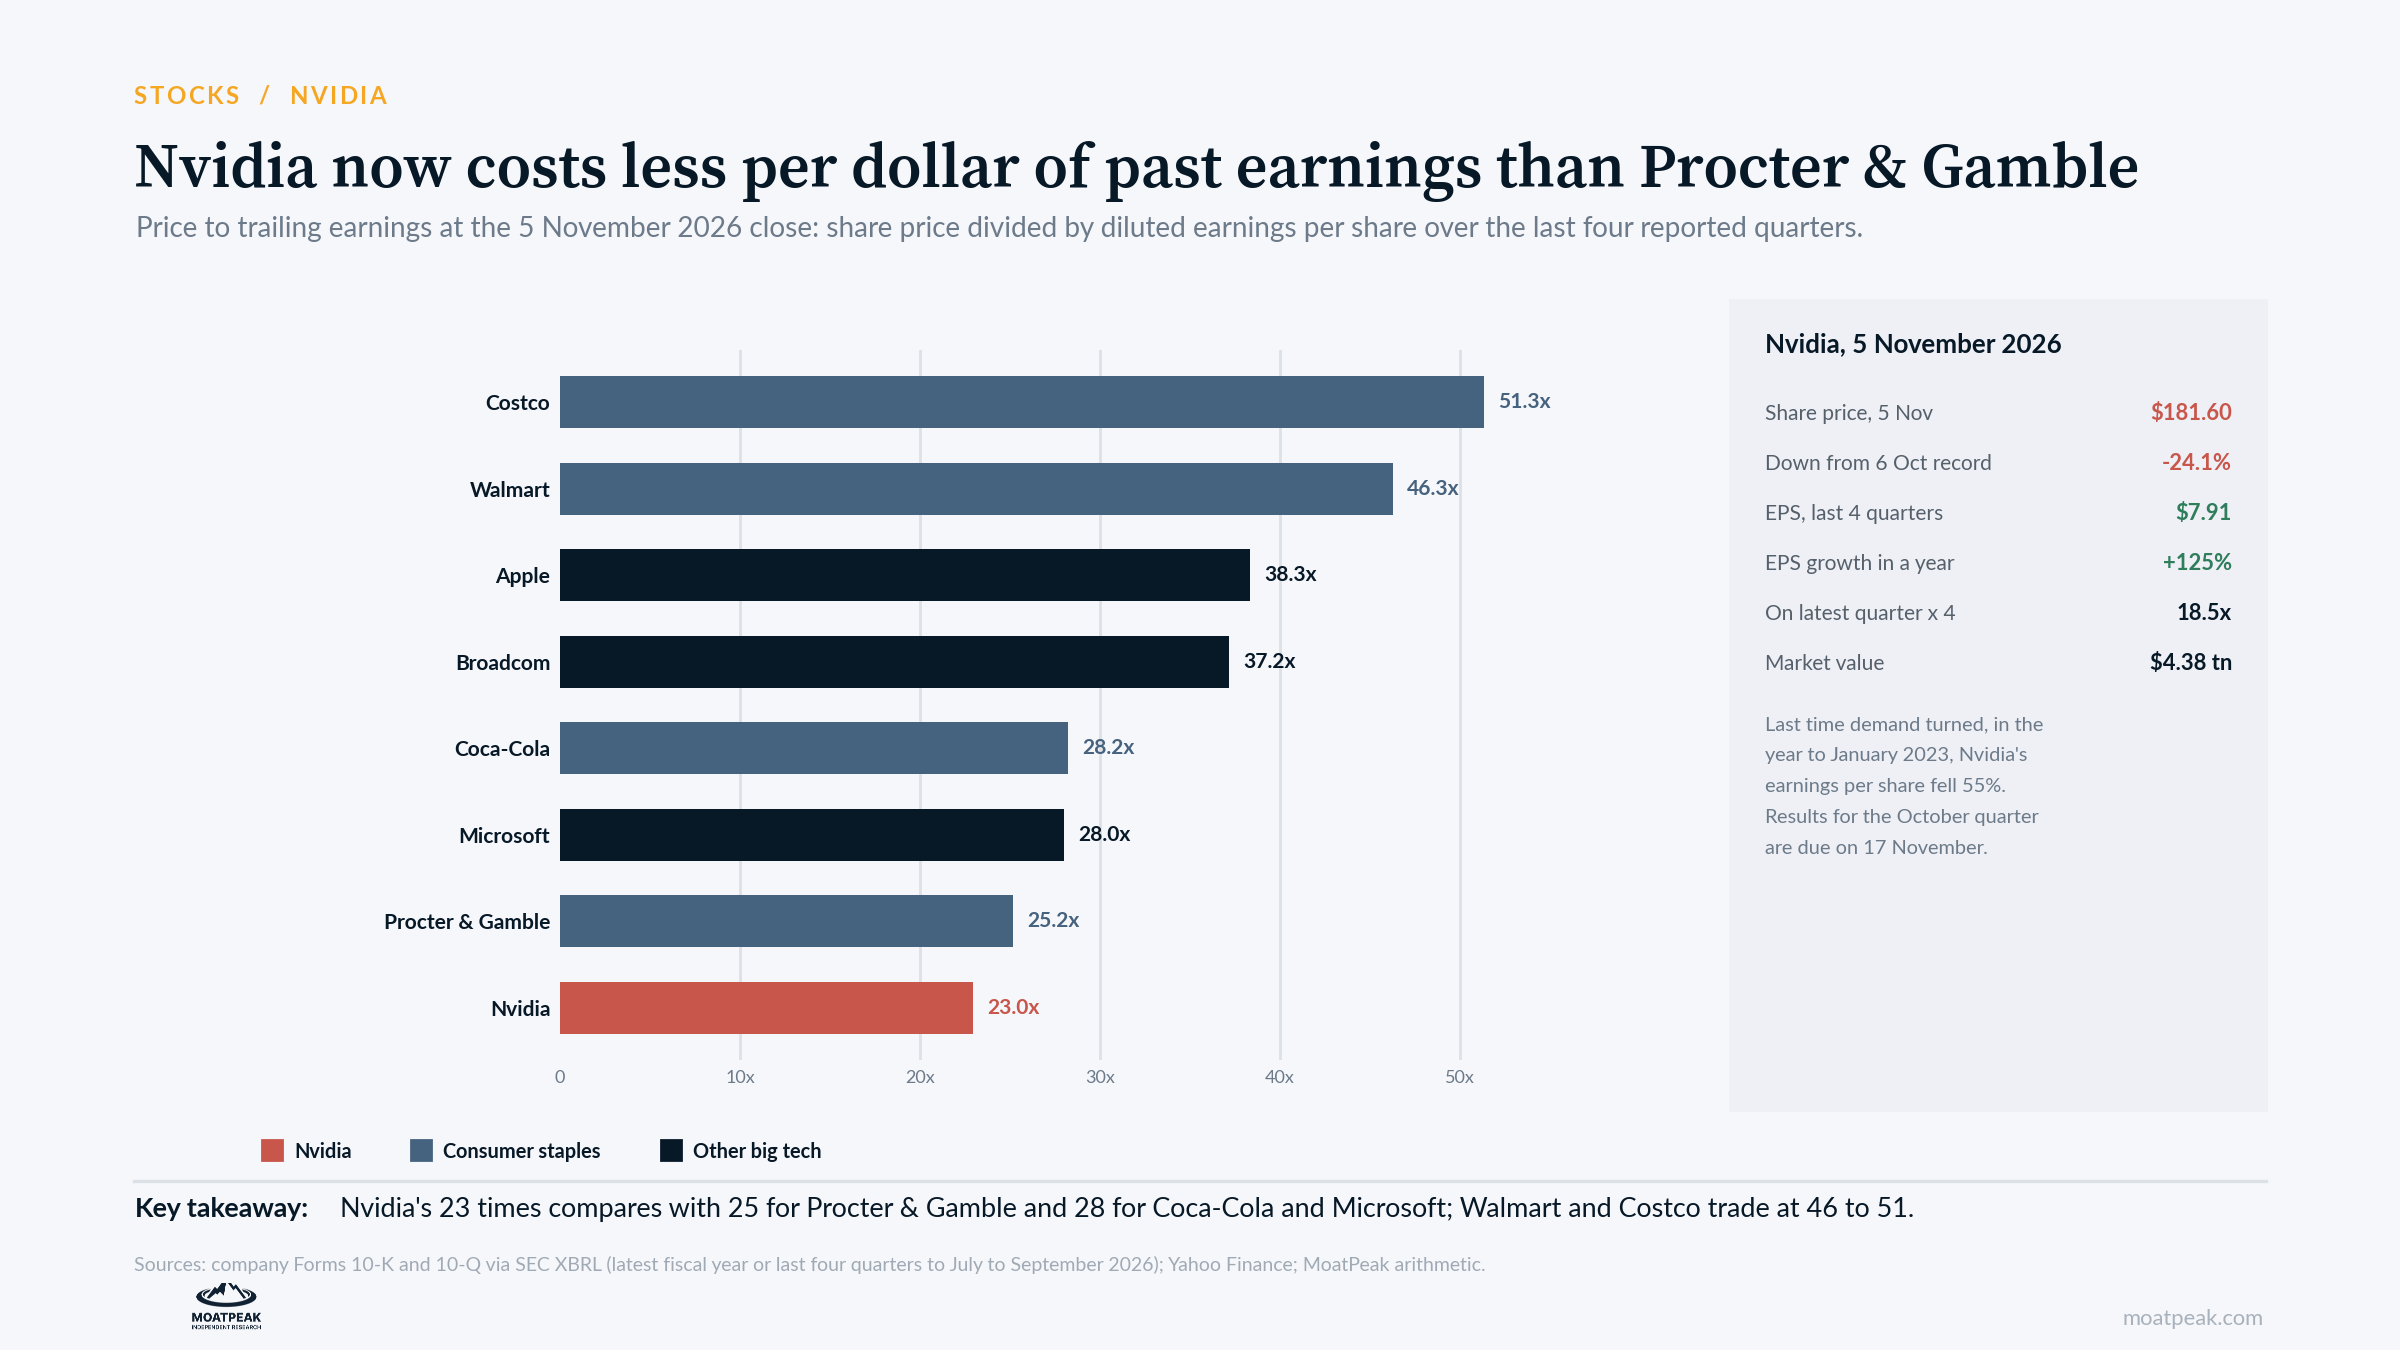
Why a growth stock trades like a staple
A low multiple on fast-growing earnings signals doubt about how long those earnings will last. Procter & Gamble trades at 25 times because its profits barely change from year to year. Nvidia’s profits depend on what a handful of cloud giants spend on data centers.
That spending is extraordinary. Microsoft, Alphabet, Amazon, Meta and Oracle spent $230 billion on property and equipment in their latest quarters, 118 percent more than a year earlier. Nvidia’s revenue in the July quarter was $96.2 billion, more than double a year earlier.
Spending cannot double every year for long. For cyclical companies, the multiple usually looks lowest when earnings are at their peak, which is when the shares carry the most risk. The market now prices Nvidia that way.
The last downturn
Nvidia has been through this before. In the fiscal year to January 2023, its earnings per share fell 55 percent.
A drop half that size would change the picture. If earnings fell 27.5 percent from here, the $181.60 stock would trade at 32 times earnings, more than the 30 it fetched at its 6 October record. On the latest quarter’s earnings of $2.46 a share, annualized, the multiple is 18.5.
Our read
The market already prices Nvidia as a cyclical business at peak earnings, and we think that description is fair. At 23 times, the stock offers good value only if customers’ 2027 budgets hold near this year’s level. The first evidence arrives with the 17 November results.
The case against us
Demand shows no sign of slowing yet. Revenue rose $14.6 billion from the April quarter to the July quarter, and the biggest customers’ capital spending was still up 118 percent from a year earlier.
The multiple already discounts a lot. At 23 times, investors are paying less for Nvidia’s earnings than at any point in our weekly data since May 2024, including the April 2025 low of 32.
What it means for your money
Test the price against lower earnings. At $181.60, a 25 percent fall in earnings would lift the multiple to 31, and a 50 percent fall to 46.
Watch the customers’ budgets. The cloud giants’ plans for 2027 will matter more than any one Nvidia quarter.
Size it like a cyclical. The shares fell 24 percent in a month without any drop in reported earnings.
What we are watching
17 November: Nvidia’s results for the quarter that ended 25 October and its guidance for the January quarter.
Late January and early February: 2027 spending plans from Microsoft, Alphabet, Amazon and Meta.
Gross margin: the first place pricing pressure would show if demand cools.
Educational research only. Not personalized investment advice. MB “MoatPeak Group”.
This is the clearest way I have seen the Nvidia puzzle put. The 23 times number looks cheap until you remember what a low multiple means for a cyclical, and the 55 percent fall in earnings per share in the year to January 2023 is the warning. I keep coming back to the same split you draw. The quarter on 17 November will probably be strong, because the demand is still there in the numbers you cite. The guide is the real test, and after that it is the 2027 budgets in late January. I am not buying the cheap multiple on its own. I want to see a customer commit to next year's spend first, and I will be watching gross margin for the first sign that pricing is slipping.